

Competitiveness for Britain cannot mean what it means for the United States or China. Britain is a middle-sized, trade-dependent economy. It cannot impose terms through scale, dominate technological chokepoints, or absorb external shocks with the strategic autonomy available to great powers. Its competitiveness must therefore be judged differently: by its productive strength, the positioning of its specialisations, the breadth and quality of its international links, and its capacity to manage critical dependencies without retreating from openness.
That argument crystallised for me during a panel I was on at the British Chambers of Commerce Driving International Trade Conference on Wednesday. The discussion covered the US relationship, the Iran war, the EU reset, currency markets. Every panellist was describing a different piece of the same puzzle — the stock of Britain’s reputation, the closing window for a US deal before the midterms, the fragmentation of energy markets — but nobody assembled the pieces. The real question behind all these discussions is actually this: what does competitiveness actually mean for Britain in a fragmenting world?
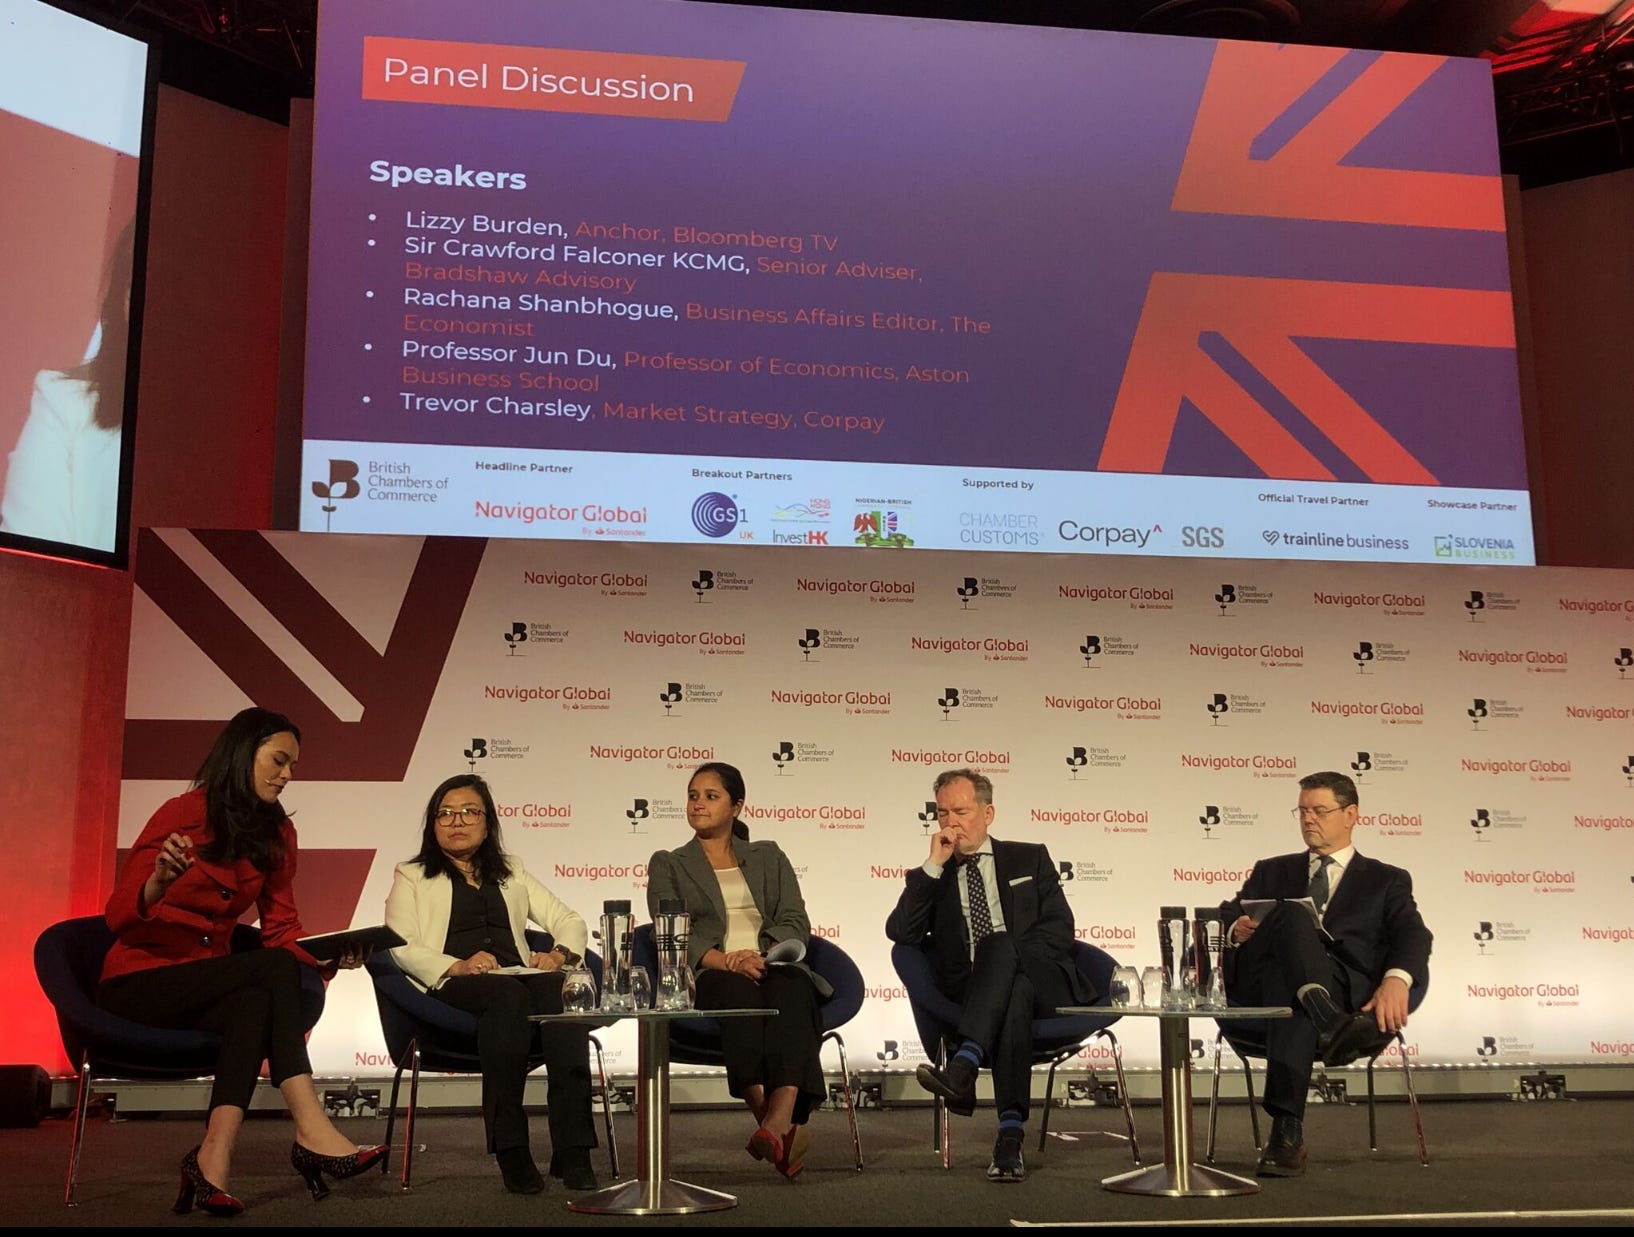
Picture credit to Carla Assunção MCIEx, at https://shorturl.at/C8SCk
The frameworks don’t fit
The conventional competitiveness frameworks — Porter’s diamond, composite indices, league table rankings — were designed for an era of stable, rules-based trade. They measure productivity and institutional quality. These matter, but they were never built to address what a trade-dependent middle power faces when the global order fragments: weaponised tariffs, contested shipping lanes, allies that coerce, and supply chains that double as geopolitical leverage.
What competitiveness looks like for a middle power
Start with the most familiar layer: productive capability. UK productivity has been essentially flat since 2008. The long tail of low-productivity firms, the poor diffusion of technology from frontier to lagging firms — this is the well-documented British disease, and it predates the current crisis. Any competitiveness strategy has to start here.
But productivity alone is not enough. It needs to be understood in the context of the productive structure of an economy — is it positioned in the right industries, and are those positions defensible? Britain has genuine strengths in financial services, life sciences, advanced engineering. Turbo-jet exports were up 47 per cent year-on-year in December 2025. But not only does the country remain under-invested in semiconductors, critical minerals, energy technology, and AI — the strengths in services may be less secure than they appear. Services have to serve someone: domestic industries, foreign firms, global consumers. As Britain and other advanced economies have become more services-oriented, those services have grown increasingly exposed to the shifting dynamics of trade and investment flows. Financial services depend on the health of global capital markets. Professional services depend on the firms and sectors they advise. Higher education depends on international student demand. These inter-industry dependencies are less understood than goods-trade vulnerabilities, and rarely stress-tested.
The government’s industrial strategy identifies growth sectors, which is the right instinct. The opportunity now is to strengthen the evidence base underpinning those choices, particularly as global conditions have shifted significantly since the initial analysis.
Then there is the quality and diversity of Britain’s international integration. The DHL Global Connectedness Report 2026found that the UK has the most broadly distributed trading relationships of any country in the world. That breadth — the spread of links across regions, not just their depth — is a strategic asset no league table captures, and one that trade policy should be designed to protect.
Vulnerability is not the same as dependence
Beyond productivity, sector mix, and trade breadth, there is a dimension of competitiveness that UK policy essentially ignores: resilience to coercion and disruption.
Dependence and vulnerability are not the same thing. An economy can depend heavily on imported inputs and face no meaningful risk if those imports come from diversified, stable sources. Equally, a country can appear self-sufficient and still be acutely exposed if a single chokepoint — an energy route, a rare earth processor, a data cable — is vulnerable to disruption. The Iran war is a live demonstration: roughly a fifth of global oil and LNG flows move through the Strait of Hormuz, and Britain still runs much of its industrial base on gas.
The harder question is what to do once the distinction is clear. For genuine vulnerabilities, the logic points in two directions at once. The long-term work is structural: building the domestic foundations — in energy, in critical inputs, in technological capacity and sovereignty in some cases — that close the gaps before vulnerability becomes crisis. But structural transformation takes time, and in the interim, the only way to buy that time is to maintain and deepen relationships with the very partners who could pose a threat. That is why Britain cannot afford to choose between the United States and China — at least not yet. As my research with Oleksandr Shepotylo has shown, the worst outcomes for Britain come precisely when it is forced into bloc-based choices that its economic structure cannot sustain.
As I argued in a recent Project Syndicate piece, the 2025 US tariffs showed that there were no strategic winners — only countries that lost less, and the distinguishing factor was adaptive capacity, not comparative advantage in the traditional sense. That is the world Britain now has to compete in.
There is a saying in Chinese: 弱国无外交 — a weak country has no diplomacy. The English equivalent is blunter: dependence narrows the room for manoeuvre. A country that relies on others cannot set the terms on which it engages with them. That is precisely why building structural resilience is urgent — it is the precondition for genuine strategic choice.
The missing piece
After the panel, a manufacturer came over — 400 employees, 55 years in business, agricultural machinery. She described the bind my research keeps documenting: competitive domestically but struggling in European markets because the company’s economies of scale are built for the UK market. Add customs friction, energy costs, and more price-aggressive European consumers, and the maths doesn’t work. “We are not in any clubs,” she said. “We’re completely enclosed.” This is a story I am all too familiar with after years of studying UK trade post Brexit — from the early trade effects to the industry-level damage across most sectors, the missed trade benefit of SPS agreement for agrifood exporter, and the case for mutual recognition of conformity assessment.
Her story illustrates something the competitiveness debate consistently underweights. For firms like hers, the most damaging loss of competitiveness came not from global fragmentation but from the increase in trade friction with the EU — Britain’s largest and nearest market. For many firms, especially in manufacturing, reducing that friction is still likely to be among the highest-return trade policy moves available to the UK government. It is not glamorous, and it is politically constrained, but the gravity model doesn’t care about politics.
But even if EU friction were resolved tomorrow, the deeper problem remains. Firms like hers — productive, exporting, employing hundreds of people — do not fall neatly into the government’s eight strategic growth sectors. The productivity challenge for Britain is not only about pushing the frontier in AI or life sciences. It is also about the vast number of capable firms outside that framework whose productivity determines the actual living standards of most of the country. Finding ways to support their competitiveness cannot be a sideshow to the growth agenda.
Why it matters beyond growth
And there is a political economy reason why this matters beyond growth itself. When the gains from trade and industrial strategy concentrate in certain regions and sectors, the political basis for openness erodes. That is part of what produced Brexit — decades of spatially concentrated prosperity generating a backlash that disrupted the country’s entire trade architecture. If the benefits of any future competitiveness strategy don’t reach firms and people like hers, the next populist shock will be worse than the last one. This isn’t a moral argument — it’s an analytical one.
Britain needs the map
The country doesn’t yet have a framework for thinking about its competitiveness that matches the world it actually inhabits. I’m working on a more formal treatment of this, but the conference crystallised the urgency.
What Britain needs is a competitiveness framework that links industrial strategy, trade policy, infrastructure investment, energy security, and the management of strategic dependencies — rather than treating them as separate policy silos run by separate departments with separate logics. Without that integration, every negotiation, every sector bet, every investment decision is improvisation. That is not a strategy.
* * *
Jun Du is professor of economics at Aston Business School, Aston University. She spoke at the BCC Driving International Trade Conference on 26 March 2026.
Really enjoyed this analysis - insightful and engaging. I agree we need to think much more structurally about competitiveness. Not optimistic that any political outcome will support this but that does not prevent our businesses and our other institutions, especially universities doing the right thing.
Three questions this sparked for me:
1. No mention of demographics. I feel this is a massive influence on both current and longer term economic shifts.
2. While I agree we should not ignore China, it feels like there are really four poles: US, China, EU and India - does this make sense?
3. What role does innovation and entrepreneurship play in driving competitiveness? We should be leading in this, especially given the strength of our universities. But it feels like we are under performing and government action is making things worse not better.
Thanks for the post Jun Du - really excellent